

Demolition – Reconstruction: In Which Cases Can the 6% VAT Rate Apply?
For several years, the VAT regime applicable to demolition and reconstruction projects of residential buildings has undergone numerous changes.
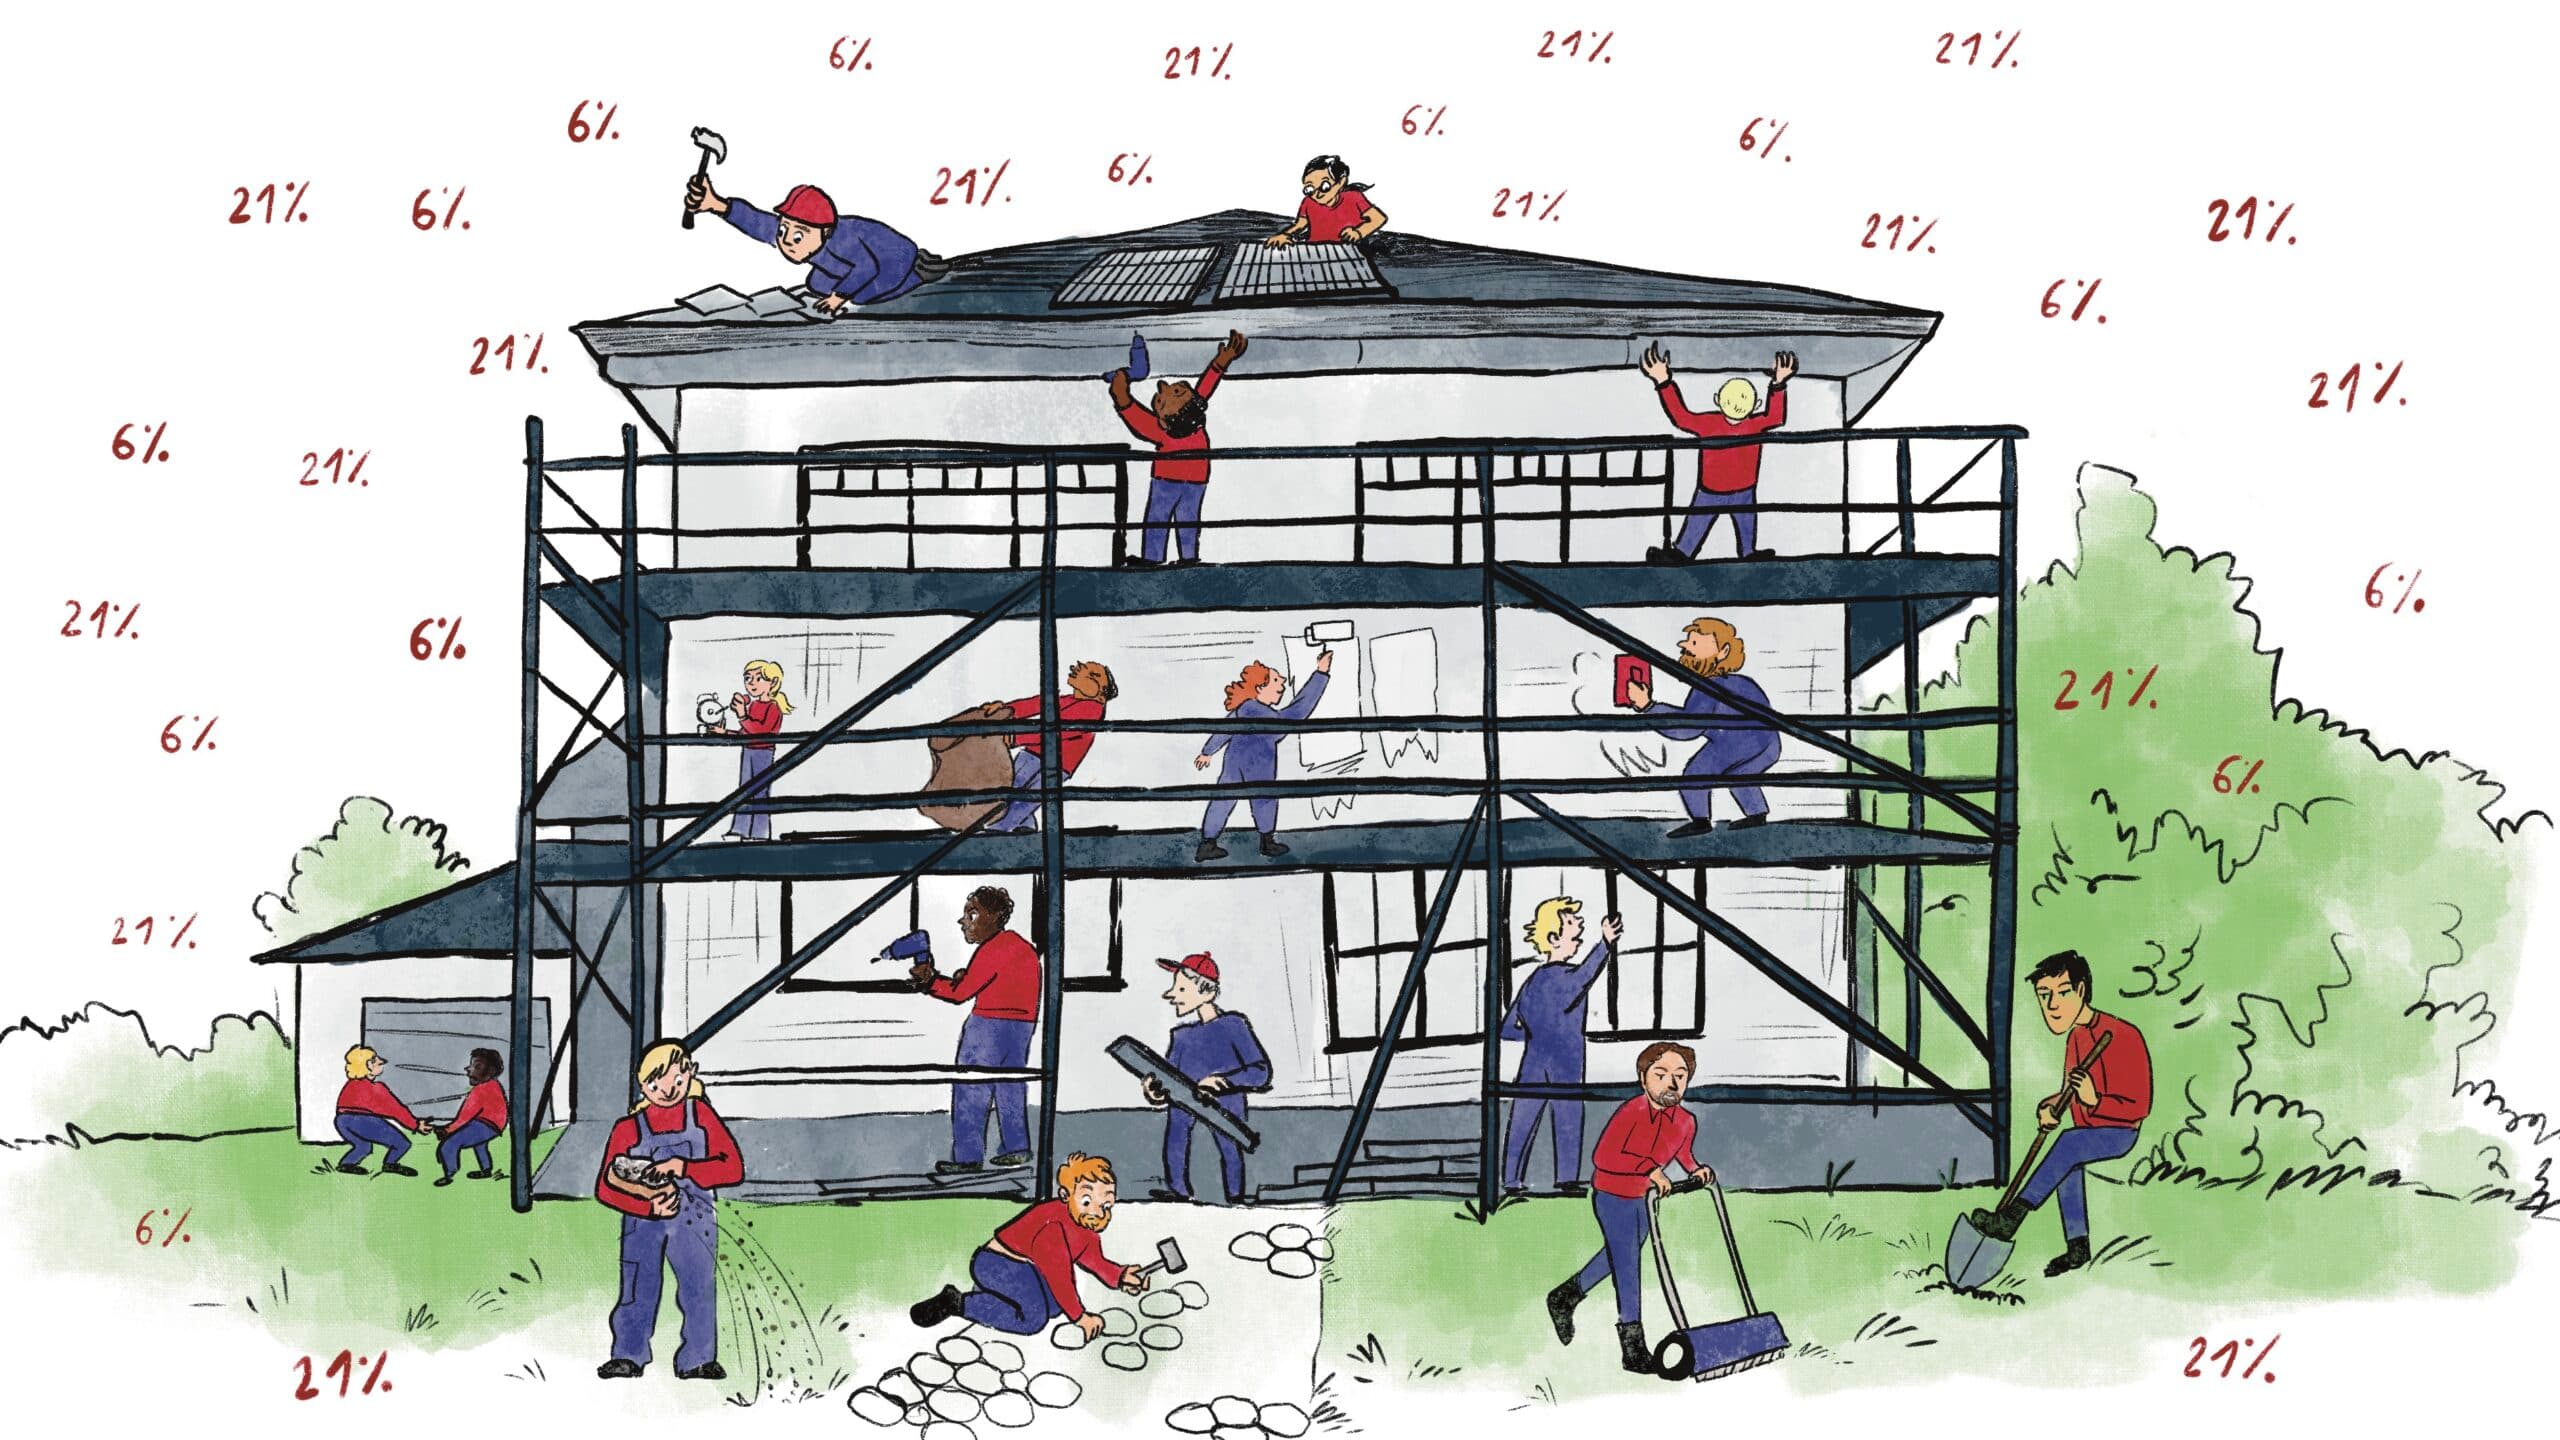
The Programme Law of 18 July 2025 introduced a permanent regime, applicable as from 1 July 2025, allowing, in certain cases, the application of the reduced VAT rate of 6% both to construction works and to the sale of a reconstructed dwelling.
Given the complexity of the regime and the significant number of conditions to be verified, our firm has developed a tool enabling a rapid assessment of whether a project may benefit from the 6% VAT rate in the context of demolition and reconstruction.
In order to better understand how this tool operates, it is appropriate to briefly recall the different applicable regimes.
1. VAT Regimes Applicable to Construction Works
Where the works involve the demolition of a building followed by the reconstruction of a dwelling, the 6% VAT rate may apply in three situations.
1.1 Reconstruction Intended for the Owner’s Own Occupation
The first regime concerns the situation in which a natural person has a building demolished in order to reconstruct their own dwelling.
The reduced rate may be applied provided, in particular, that:
- the dwelling is used as the sole and principal residence of the owner;
- the owner establishes their domicile there without delay;
- the habitable surface area does not exceed 200 m²;
- these conditions are complied with until 31 December of the fifth year following that of the first occupation or use of the building.
This regime primarily targets private individuals who rebuild their home on land containing an existing building.
1.2 Reconstruction Intended for Letting Under the Social Housing Policy
The 6% VAT rate may also apply where the reconstructed building is rented out within the framework of the social housing policy.
In this case, the developer (natural or legal person) must lease the dwelling, for a minimum period until 31 December of the fifteenth year following that of the first occupation or use of the building, to a social housing operator, such as a social rental agency, a public housing company, or another organisation recognised under the social housing policy.
No maximum surface area condition applies under this regime, which is primarily intended for investments in social housing.
1.3 Reconstruction Intended for Long-Term Private Rental
A third regime applies to the reconstruction of a dwelling intended for long-term private rental.
In this case:
- the dwelling must be rented directly to a natural person who will establish their principal residence there;
- the habitable surface area must not exceed 200 m²;
- the lease must be maintained until 31 December of the fifteenth year following that of the first occupation or use of the dwelling.
This regime is mainly aimed at long-term rental investment projects.
2. VAT Regime Applicable to the Sale of a Reconstructed Dwelling
Following the reform that entered into force on 1 July 2025, the 6% VAT rate may also apply to the supply (sale) of a dwelling reconstructed after demolition, in particular within the framework of real estate development projects.
In this case, the purchaser must allocate the dwelling to one of the following uses:
- personal occupation (sole and principal residence);
- letting within the framework of the social housing policy;
- long-term private rental.
However, an important distinction must be highlighted: in cases of personal occupation or private rental, the maximum habitable surface area is limited to 175 m² at the time of the supply of the dwelling.
3. A Regime Subject to Several General Conditions
In addition to the conditions specific to each situation, the application of the reduced rate is subject to compliance with several general conditions.
Among the main conditions are:
- the existence of an actual demolition followed by reconstruction;
- the execution of the project on the same cadastral parcel;
- the allocation of the reconstructed building to private residential use;
- compliance with the surface area and use conditions specific to each regime.
The application of the reduced rate is also subject to the fulfilment of certain administrative formalities. In particular, a declaration must be submitted to the tax authorities via forms 111 available on MyMinfin, before VAT becomes chargeable on the relevant transaction.
Depending on the intended use of the reconstructed building, different forms must be used:
- 111_1-01/07/2025: own residence;
- 111_2-01/07/2025: social rental;
- 111_3-01/07/2025: supply (sale);
- 111_5-01/07/2025: long-term private rental.
Conclusion
The VAT regime applicable to demolition and reconstruction has become an important fiscal instrument for real estate projects; however, its application remains technical due to the numerous conditions set out in the legislation.
The tool developed by our firm allows for a rapid preliminary assessment of the potential application of the reduced 6% VAT rate.
Our firm remains, of course, at your disposal for any specific questions relating to the application of the reduced VAT rate in the context of a demolition–reconstruction project.
Discover more about this topic?
I am looking for a specialist in
See more articles
05.11.2026
•Real Estate, Renting and Co-ownership, Andersen in Belgium
New rules tighten requirements for sustainability claims in the real estate sector
Sustainable, green, energy-efficient or even climate-neutral: these terms have become commonplace in real estate communications. From the end of September, however, the use of such claims will be subject to stricter rules. The new rules aim to better protect consumers against misleading environmental claims. For businesses, the message is clear: commercial communications will need to be more precise.
05.11.2026
•Employment Law, Andersen in Belgium
Belgium imposes new workplace regulations
Employers must make sure that their internal policies are up date according to Belgium’s PIA and prepare for a stricter time registration obligation.
03.11.2026
•Tax Law, Andersen in Belgium
No Exact Correlation Required Between Expenses Relating to a Holiday Residence and Benefits in Kind
In its judgment of 18 June 2026, the Belgian Court of Cassation settled an important question concerning the deductibility of expenses incurred in making a holiday residence available to a company director: must these expenses be capped at the amount of the benefit in kind (BIK) taxed in the hands of the director? The Court answered in the negative.
03.11.2026
•Tax Law, Andersen in Belgium
Copyright and Tax Abuse: The Court of Cassation Gets Its Wires Crossed!
In a rather surprising judgment of 14 September 2026 (F.23.0097.F), the Belgian Court of Cassation failed to correctly identify the legislature's objectives when introducing the flat-rate tax regime for copyright and related rights income. The courts should swiftly distance themselves from this judgment!