

SEEDS OF LAW OBTAINS AN ACQUITTAL FOR A CLIENT AGAINST THE CUSTOMS AUTHORITY
In a recent judgment from the criminal court of Antwerp, a client of Seeds of Law, falsely accused of violations of the customs regulations, has been acquitted.
1. What were the facts?
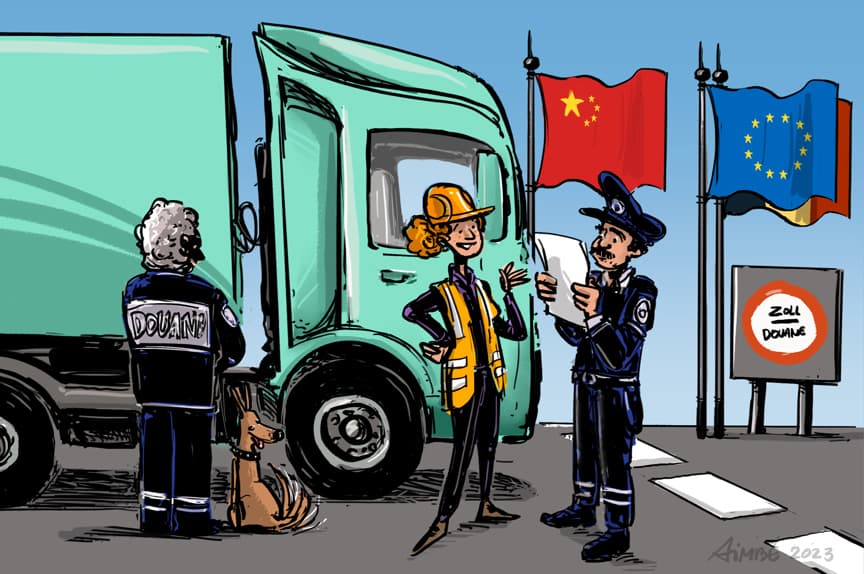
The customs authority accused the client of not having used the correct code for the goods when declaring a shipment of clothes from China. The customs authority further accused the client of not having indicated the net weight of the imported goods and of having undervalued the declared goods.
According to the customs authority, the client should have declared a much higher value, so it imposed higher customs duties, as well as a fine. The client received several proposals for out-of-court settlement, with a request for payment. Refusal to accept the proposed settlement would lead to the goods being seized followed by a criminal prosecution.
Seeds of Law disputed the arguments of the customs authority, at first in administrative proceedings where it submitted an apprehensive dossier in which each single one of the arguments of the customs authority was dismissed. Every petition filed was answered by the customs authority by sending the same proposal of out-of-court settlement, without responding to the arguments invoked by the client. The customs authority had also seized the client’s goods. The client had to pay a deposit for the release of its goods so it could comply with its obligations to deliver to its customers – retailers. The amount of the deposit was the same as the amount of the increased customs duties and the fine.
The client was even interrogated by the authorities. During this interrogation, Seeds of Law once more tried to argue that the declaration was correctly filed, but again, we received the same proposal of out-of-court settlement as sole response. The client still refused to pay and eventually was summoned to appear in criminal court.
2. Seeds of Law obtained an acquittal
The criminal court of Antwerp acquitted the client for the charges regarding the code used and the omission of the net weight. The code used by the client for years, is actually interchangeable with the code that the customs authority considers as the correct one.
The court even remarked that both codes lead to the same amount of customs duties and ruled that the authority did not provide evidence that an incorrect code has been used.
Regarding the omission of the net weight, the client remarked that the client indeed only indicated the gross weight, but that this does not constitute a punishable offense. The client was therefore acquitted for these charges.
The valuation of the goods for the calculation of the customs duties is regulated in the Union Customs Code (hereafter UCC), which provides a stepped system of methods for the valuation of goods.
The primary basis for the customs value of goods shall be the transaction value, that is the price actually paid or payable for the goods sold for export to the customs territory of the Union. This value can possibly be supplemented by certain elements incurred by the buyer that are not included in the transaction value, such as commissions and brokerage, the cost of packing, and so on. The provisions of the UCC also provide which elements are not to be included in the customs value, such as costs of transport of the imported goods after entry into the customs territory or charges for construction of the imported goods.
The transaction value method must be used when certain conditions are fulfilled. Only when the transaction value method cannot be used, may the customs authority use secondary methods as provided for in the UCC.
In the case at hand, however, the customs authority refused to use the transaction value method, but failed to establish why this primary method could not be used. The customs authority found that it should not use the first five steps of the cascade in the client’s case. It therefore used the last step, the method of the ‘reasonable means’. It compared the value declared by the client – the transaction value – with the list of the average European values (Market Access Database – MADB).
We argued that this additional method could not be used, and if the customs authority did want to make a comparison with this list, the authority needed to consider the specific parameters presented by the client in order to justify the higher transaction value (quality, used fabric, the original purchase price, the country of origin, etc.).
The court found that the fact that the value can considerably vary in function of quality, the brand name, and the purchased volume also means that the statistical data based on the codes given to goods cannot be used as sole standard to argue that the invoiced value would be suspiciously low. The average values used are determined based on statistical data per code of goods, per land of origin, and per land of destination. By using the code of goods, for many goods, these average values give a distorted image. The court ruled that no evidence was provided establishing that the declared transaction value would not be correct and acquitted the client. The tax claim, based on a so-called erroneous declaration, was also rejected.
We had hoped that the court would have ruled that the customs authority unjustly proceeded to the valuation of the goods by using the last step, the method of the ‘reasonable means’, and thus disregarding the cascade system. Nonetheless, the court acquitted the client.
The customs authority appealed this court decision.
We shall keep you informed.

Discover more about this topic?
I am looking for a specialist in
See more articles
05.11.2026
•Real Estate, Renting and Co-ownership, Andersen in Belgium
New rules tighten requirements for sustainability claims in the real estate sector
Sustainable, green, energy-efficient or even climate-neutral: these terms have become commonplace in real estate communications. From the end of September, however, the use of such claims will be subject to stricter rules. The new rules aim to better protect consumers against misleading environmental claims. For businesses, the message is clear: commercial communications will need to be more precise.
05.11.2026
•Employment Law, Andersen in Belgium
Belgium imposes new workplace regulations
Employers must make sure that their internal policies are up date according to Belgium’s PIA and prepare for a stricter time registration obligation.
03.11.2026
•Tax Law, Andersen in Belgium
No Exact Correlation Required Between Expenses Relating to a Holiday Residence and Benefits in Kind
In its judgment of 18 June 2026, the Belgian Court of Cassation settled an important question concerning the deductibility of expenses incurred in making a holiday residence available to a company director: must these expenses be capped at the amount of the benefit in kind (BIK) taxed in the hands of the director? The Court answered in the negative.
03.11.2026
•Tax Law, Andersen in Belgium
Copyright and Tax Abuse: The Court of Cassation Gets Its Wires Crossed!
In a rather surprising judgment of 14 September 2026 (F.23.0097.F), the Belgian Court of Cassation failed to correctly identify the legislature's objectives when introducing the flat-rate tax regime for copyright and related rights income. The courts should swiftly distance themselves from this judgment!