

VAT: Demolition/Reconstruction: Deal kept?
In order to avoid contradicting rules in our country's various regions, the federal government had announced in its coalition agreement that it was essential that projects carried out by professionals could also be marketed at the reduced VAT rate of 6% for demolition and reconstruction.
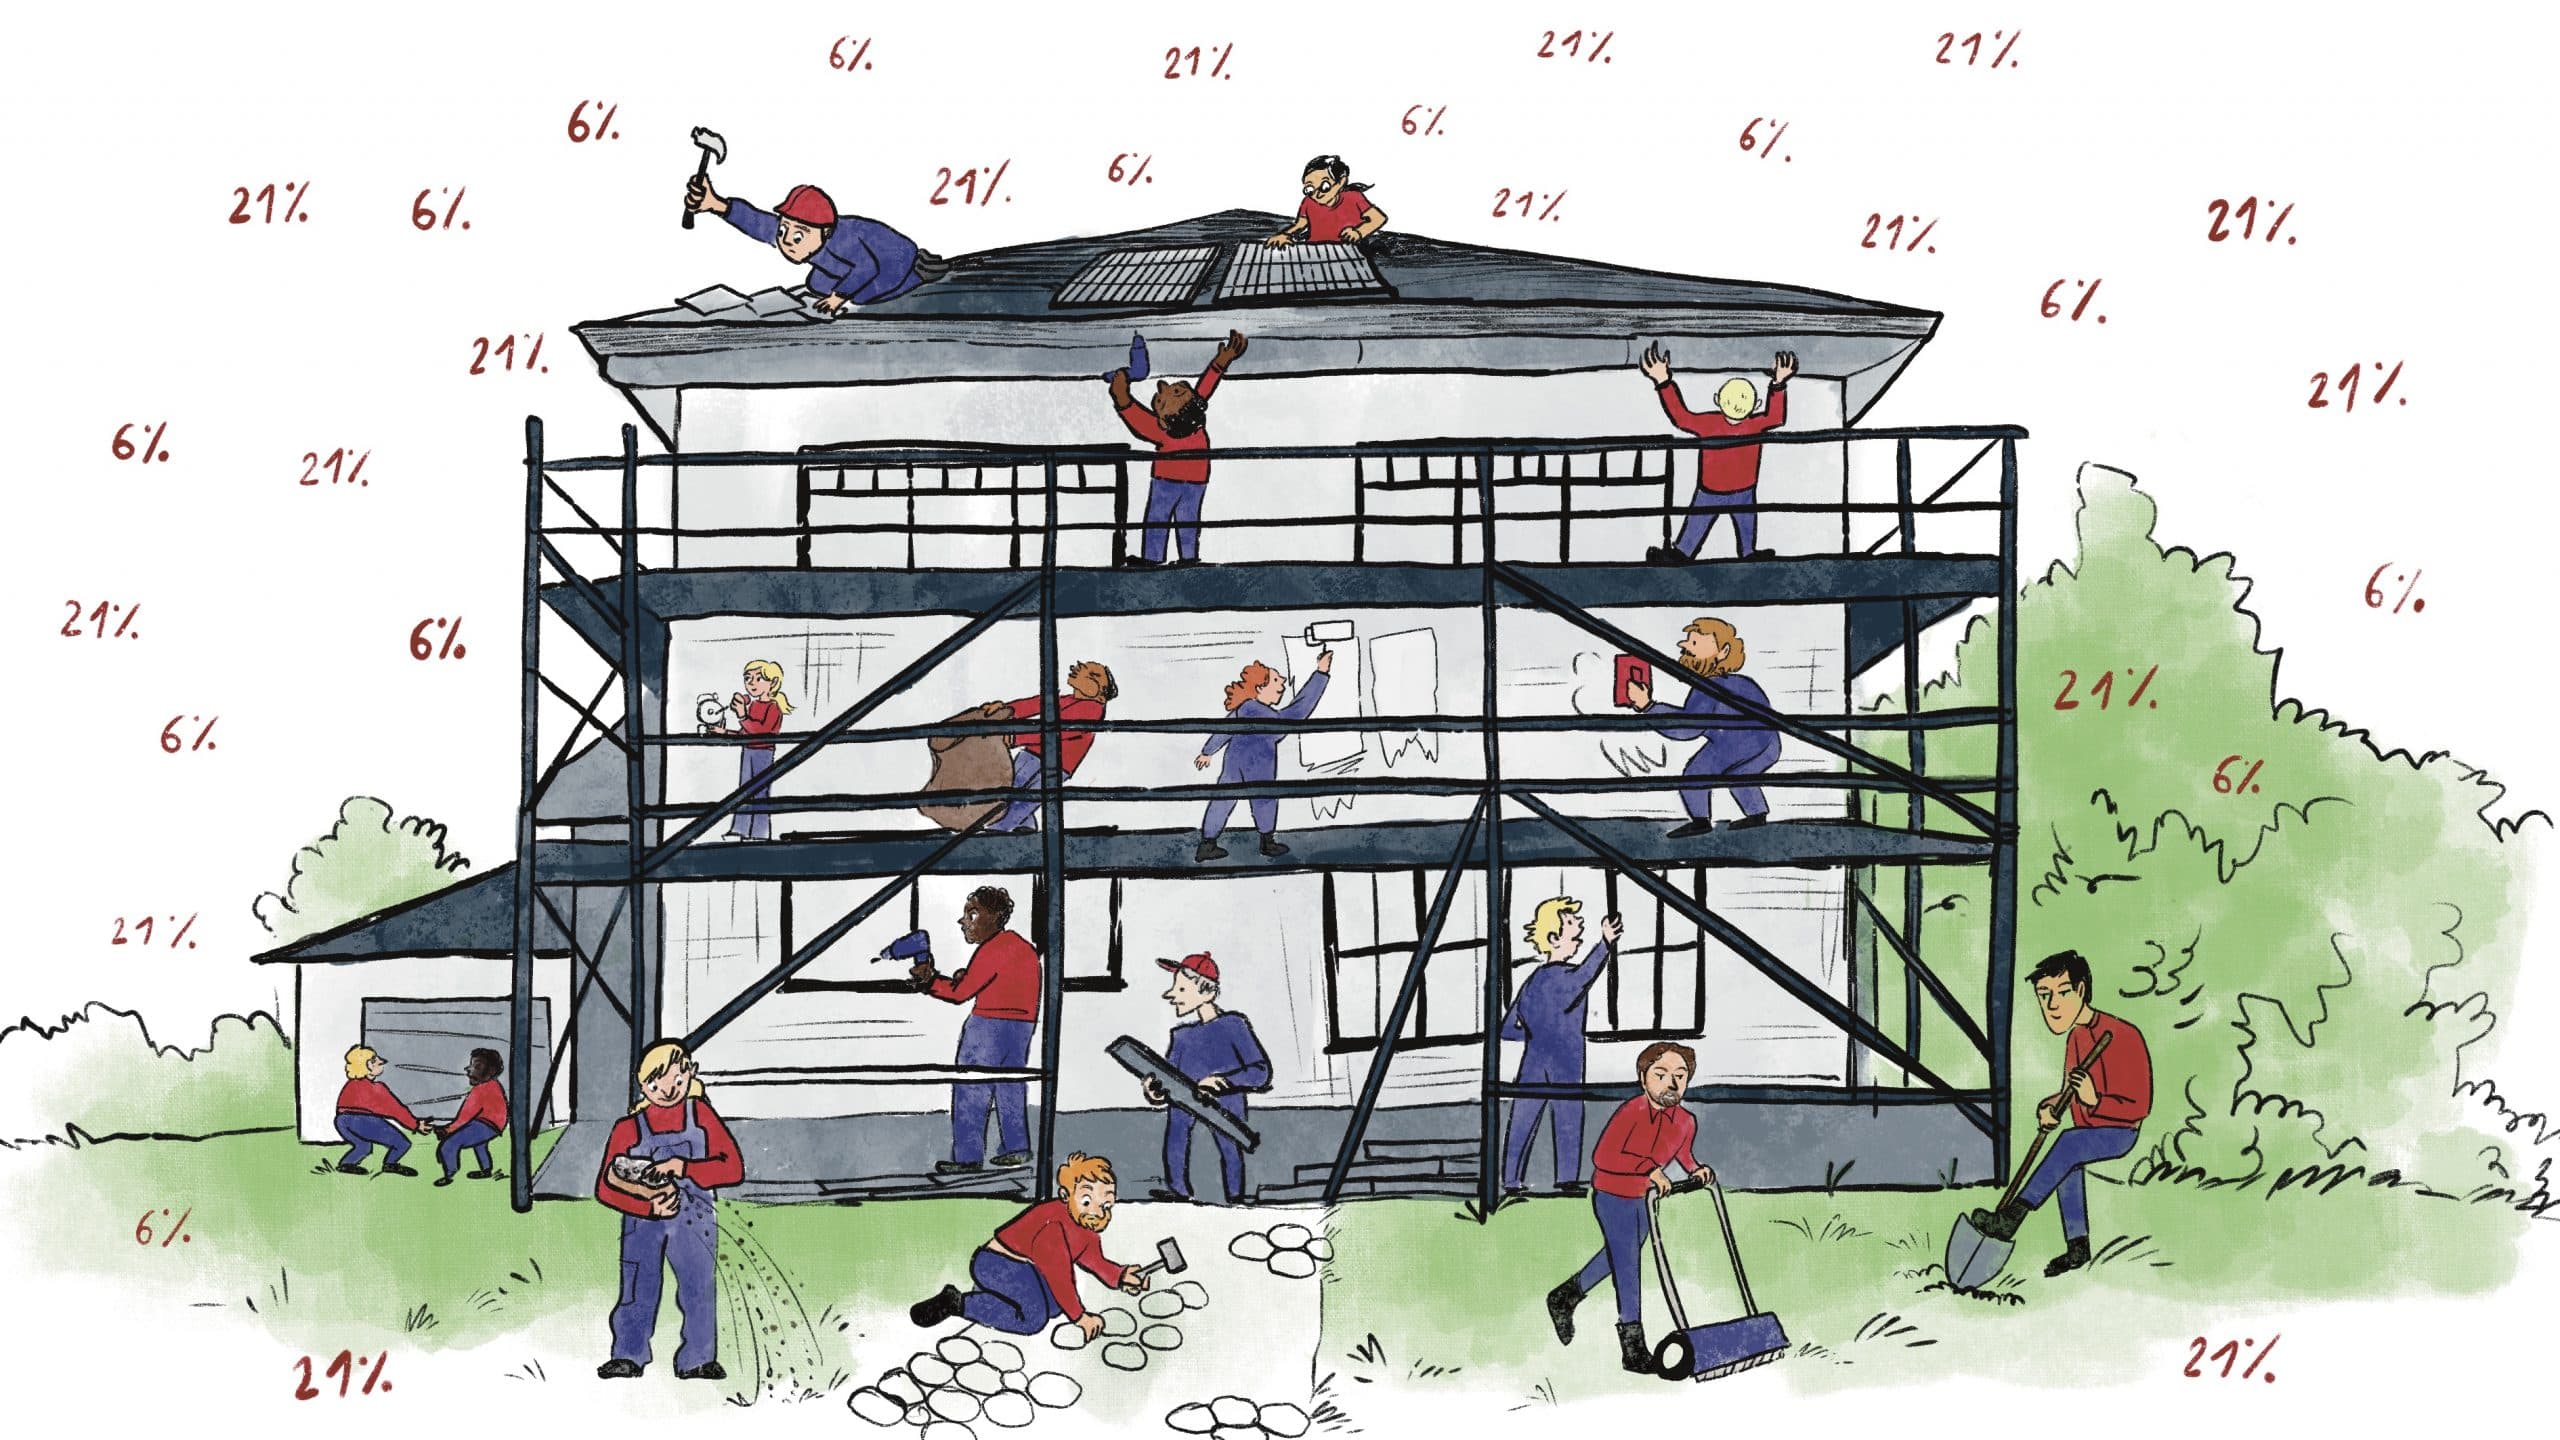
The reduced rate of 6% was to apply to everyone!
As a result, current social conditions would be maintained, and the surface criterion would be tightened from 200m2 to 175m2 for delivery.
The draft program law mentions the following different situations:
- For the principal – individual, the conditions for obtaining the scheme will be (unless amended):
- After completion of the work:
- The principal-individual uses the building as the sole and principal owner occupied dwelling and establishes its domicile there ;
- The living surface area is maximum 200m2 ;
- Electronic declaration to the Minister of Finance (+ copy to service providers):
- The planning permission; and
- The building contracts;
- Tax due no later than 31/12 of the year of first occupation;
- Invoices issued by the service providers must mention the elements justifying the application of the reduced rate, to release the service providers from their liability.
- Invoices issued by the service providers must mention the elements justifying the application of the reduced rate, to release the service providers from their liability.
- Invoices issued by the service providers must mention the elements justifying the application of the reduced rate, to release the service providers from their liability.
- After completion of the work:
- The reduced rate will still be applied to current social benefits (long-term social rental).
- For the principal – legal entity – the conditions for obtaining the scheme will be (unless amended):
- Demolition-reconstruction of a building located on the same cadastral parcel;
- Tax liability from June 1, 2025;
- Destination:
- for own and sole habitation of an individual whose living area is maximum 175m2
- for long-term social rental
- for long-term rental to an individual whose living area is maximum 200m2
- Electronic declaration before the time when the tax becomes due or in the case of sale on plan before the time when the taxable event occurs by attaching (+ in case of co-contractor – copy given):
- the planning permission
- the building contracts
- the private agreement or notarial deed.
- Invoices issued by service providers must mention the elements justifying the application of the reduced rate, to release the service providers from their liability.
- For long-term rental, the following conditions must be met:
- After completion of the work:
- Use as the sole and principal dwelling of the individual owner;
- Living surface area of maximum 200m2 ;
- Electronic declaration to the Minister of Finance appended (+ copy to service providers):
- the planning permission; and
- the building contract;
- Tax due no later than 31/12 of the year of first occupancy;
- Invoices issued by service providers must mention the elements justifying the application of the reduced rate to release the service providers from their liability.
- After completion of the work:
This is good news for property developers, although the difference in surface area maybe discriminatory and unfounded. In addition to using controversial criteria, the differences in figures are meaningless.
Discover more about this topic?
I am looking for a specialist in
See more articles
05.11.2026
•Real Estate, Renting and Co-ownership, Andersen in Belgium
New rules tighten requirements for sustainability claims in the real estate sector
Sustainable, green, energy-efficient or even climate-neutral: these terms have become commonplace in real estate communications. From the end of September, however, the use of such claims will be subject to stricter rules. The new rules aim to better protect consumers against misleading environmental claims. For businesses, the message is clear: commercial communications will need to be more precise.
05.11.2026
•Employment Law, Andersen in Belgium
Belgium imposes new workplace regulations
Employers must make sure that their internal policies are up date according to Belgium’s PIA and prepare for a stricter time registration obligation.
03.11.2026
•Tax Law, Andersen in Belgium
No Exact Correlation Required Between Expenses Relating to a Holiday Residence and Benefits in Kind
In its judgment of 18 June 2026, the Belgian Court of Cassation settled an important question concerning the deductibility of expenses incurred in making a holiday residence available to a company director: must these expenses be capped at the amount of the benefit in kind (BIK) taxed in the hands of the director? The Court answered in the negative.
03.11.2026
•Tax Law, Andersen in Belgium
Copyright and Tax Abuse: The Court of Cassation Gets Its Wires Crossed!
In a rather surprising judgment of 14 September 2026 (F.23.0097.F), the Belgian Court of Cassation failed to correctly identify the legislature's objectives when introducing the flat-rate tax regime for copyright and related rights income. The courts should swiftly distance themselves from this judgment!