

The EU’s New Mandatory “Withdrawal Button”: Key Compliance Steps for Online Traders Before June 2026
A new EU requirement will soon oblige online traders to make the exercise of the consumer’s right of withdrawal as simple and accessible as the online conclusion of the contract itself. Below, we explain what this obligation entails and what you should do to prepare.
1. Background and scope of the new obligation
Directive (EU) 2023/2673, amending Directive 2011/83/EU as regards financial services contracts concluded at a distance and repealing Directive 2002/65/EC, inserts a new Article 11a into the Consumer Rights Directive. This introduces a new obligation for traders concluding distance contracts with consumers through online interfaces.
Although the Directive was adopted in the context of financial services contracts concluded at a distance, the new mechanism is broader: it expressly extends to all distance contracts for the provision of goods and services where a right of withdrawal already exists.
The key principle is straightforward: consumers must be able to withdraw from a contract online just as easily as they concluded it online.
This new mechanism does not replace or modify the existing withdrawal rules. It simply adds a new, dedicated online option alongside them.
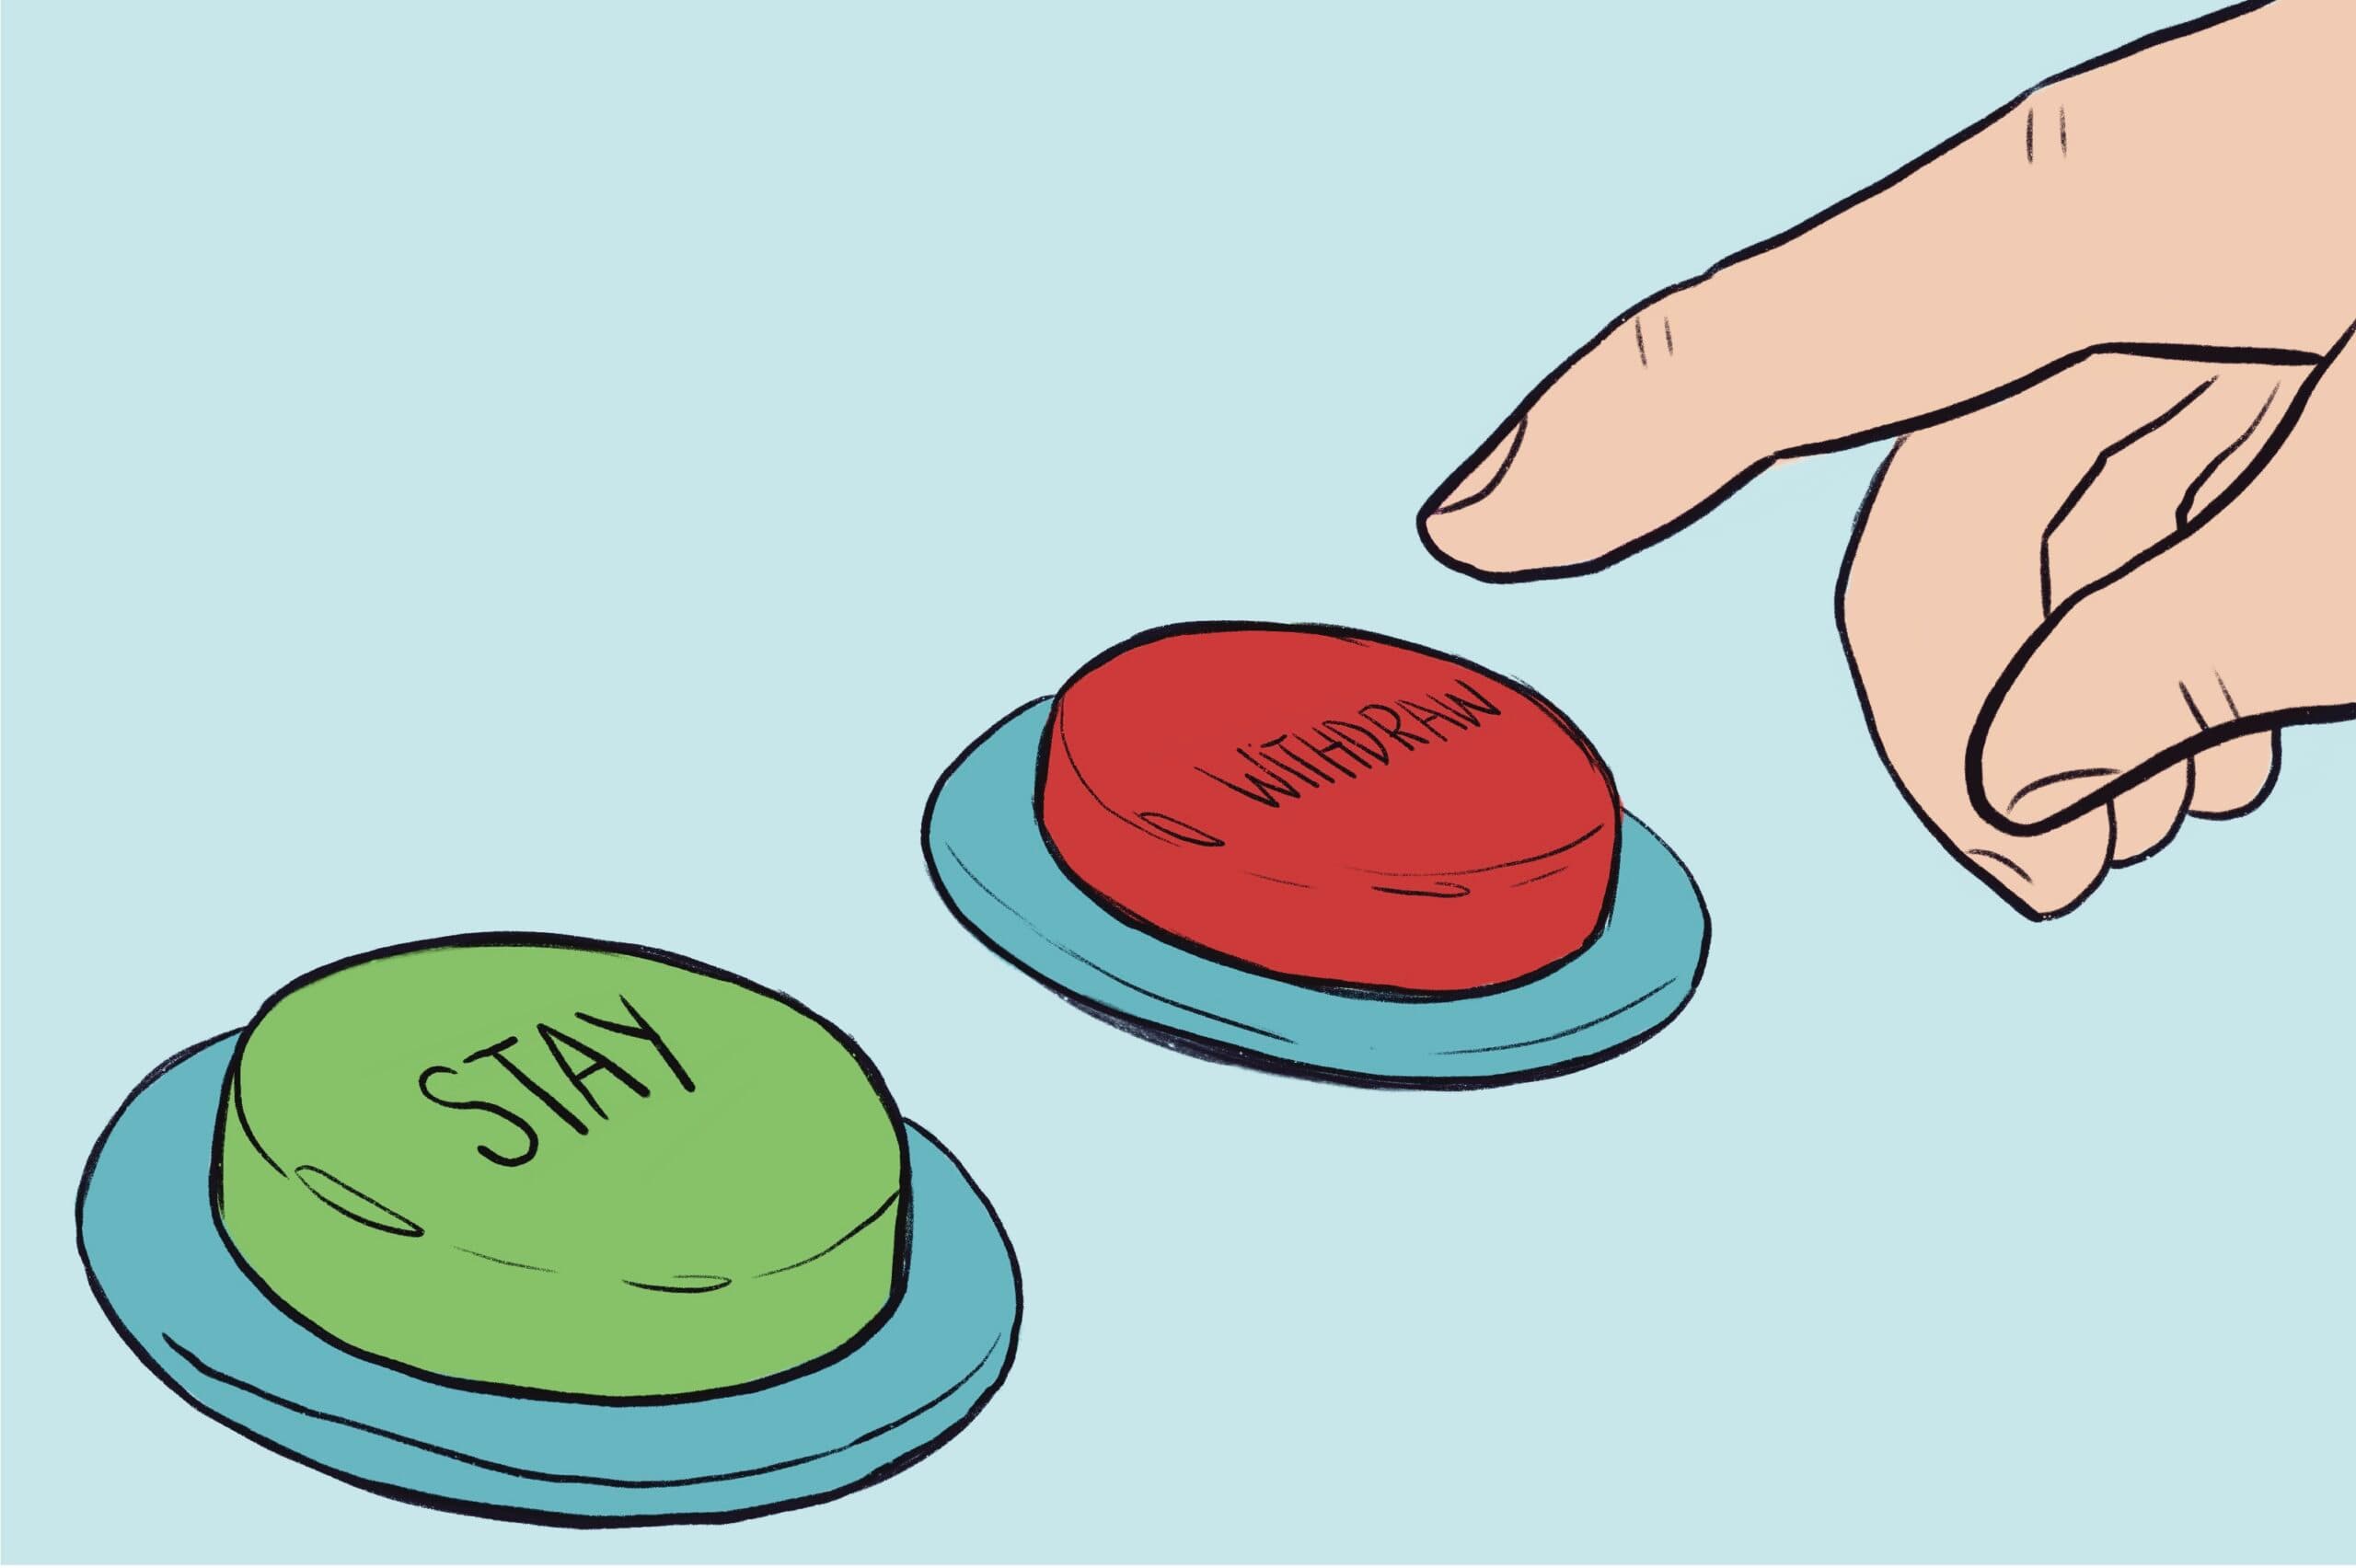
2. The “Withdrawal Button”
The Directive requires traders to implement a specific, two-step online withdrawal function.
The withdrawal function must be clearly labelled, for example with the wording “withdraw from contract here” or another equally unambiguous formulation. It must be prominently displayed, continuously available throughout the withdrawal period, and easily accessible. Consumers should not have to take unnecessary steps to find it, such as downloading an application they did not use to conclude the contract. Traders may also make the withdrawal function accessible via a direct hyperlink.
The withdrawal process must consist of two steps:
- Step 1 – Withdrawal statement: The consumer fills in an online form confirming their decision to withdraw. This form must allow them to provide or confirm their name, the identifying details of the contract, and the electronic address to which the confirmation will be sent.
- Step 2 – Confirmation: Once the statement is complete, the trader must offer a confirmation button labelled “confirm withdrawal” or an equivalent formulation. This second step is designed to prevent accidental withdrawals while keeping the process simple.
Once the consumer clicks the confirmation button, the trader must send an acknowledgement of receipt – on a durable medium and without undue delay – containing the content of the withdrawal request and the date and time it was submitted.
A consumer is considered to have exercised their right of withdrawal in time if the online withdrawal statement is submitted before the expiry of the applicable withdrawal period.
3. What this means for online traders
The withdrawal function goes beyond contractual wording. It directly affects how websites and applications are designed and operated.
Member States were required to transpose the Directive into national law by 19 December 2025. The new rules will apply from 19 June 2026.
At the time of writing, Belgium has not yet transposed the Directive into national law. The new provisions will most likely be integrated into the Belgian Code of Economic Law. In the meantime, online traders should not wait for Belgian legislation to be finalised before taking action, particularly given that several neighbouring Member States have already transposed the Directive and provide for significant sanctions for non-compliance.
We therefore recommend that online traders already review their websites, applications and withdrawal procedures to ensure full compliance by the deadline.
We will continue to monitor developments and keep you informed of any further updates on this matter.
Discover more about this topic?
I am looking for a specialist in
See more articles
05.11.2026
•Real Estate, Renting and Co-ownership, Andersen in Belgium
New rules tighten requirements for sustainability claims in the real estate sector
Sustainable, green, energy-efficient or even climate-neutral: these terms have become commonplace in real estate communications. From the end of September, however, the use of such claims will be subject to stricter rules. The new rules aim to better protect consumers against misleading environmental claims. For businesses, the message is clear: commercial communications will need to be more precise.
05.11.2026
•Employment Law, Andersen in Belgium
Belgium imposes new workplace regulations
Employers must make sure that their internal policies are up date according to Belgium’s PIA and prepare for a stricter time registration obligation.
03.11.2026
•Tax Law, Andersen in Belgium
No Exact Correlation Required Between Expenses Relating to a Holiday Residence and Benefits in Kind
In its judgment of 18 June 2026, the Belgian Court of Cassation settled an important question concerning the deductibility of expenses incurred in making a holiday residence available to a company director: must these expenses be capped at the amount of the benefit in kind (BIK) taxed in the hands of the director? The Court answered in the negative.
03.11.2026
•Tax Law, Andersen in Belgium
Copyright and Tax Abuse: The Court of Cassation Gets Its Wires Crossed!
In a rather surprising judgment of 14 September 2026 (F.23.0097.F), the Belgian Court of Cassation failed to correctly identify the legislature's objectives when introducing the flat-rate tax regime for copyright and related rights income. The courts should swiftly distance themselves from this judgment!